Financial markets in upheaval: significant shifts beneath the surface
Economy picks up
In the first few weeks of the year, the media discourse was dominated almost exclusively by geopolitical tensions. The actual economic event almost faded into the background: global economic momentum is gaining noticeable momentum. It is being driven by structural forces that we have been discussing for some time: high global government spending, a broad-based investment cycle and increasingly tangible productivity gains through the use of artificial intelligence.
The awakening of industry is particularly pleasing. After three years of recession, the global manufacturing industry is returning to expansion mode.
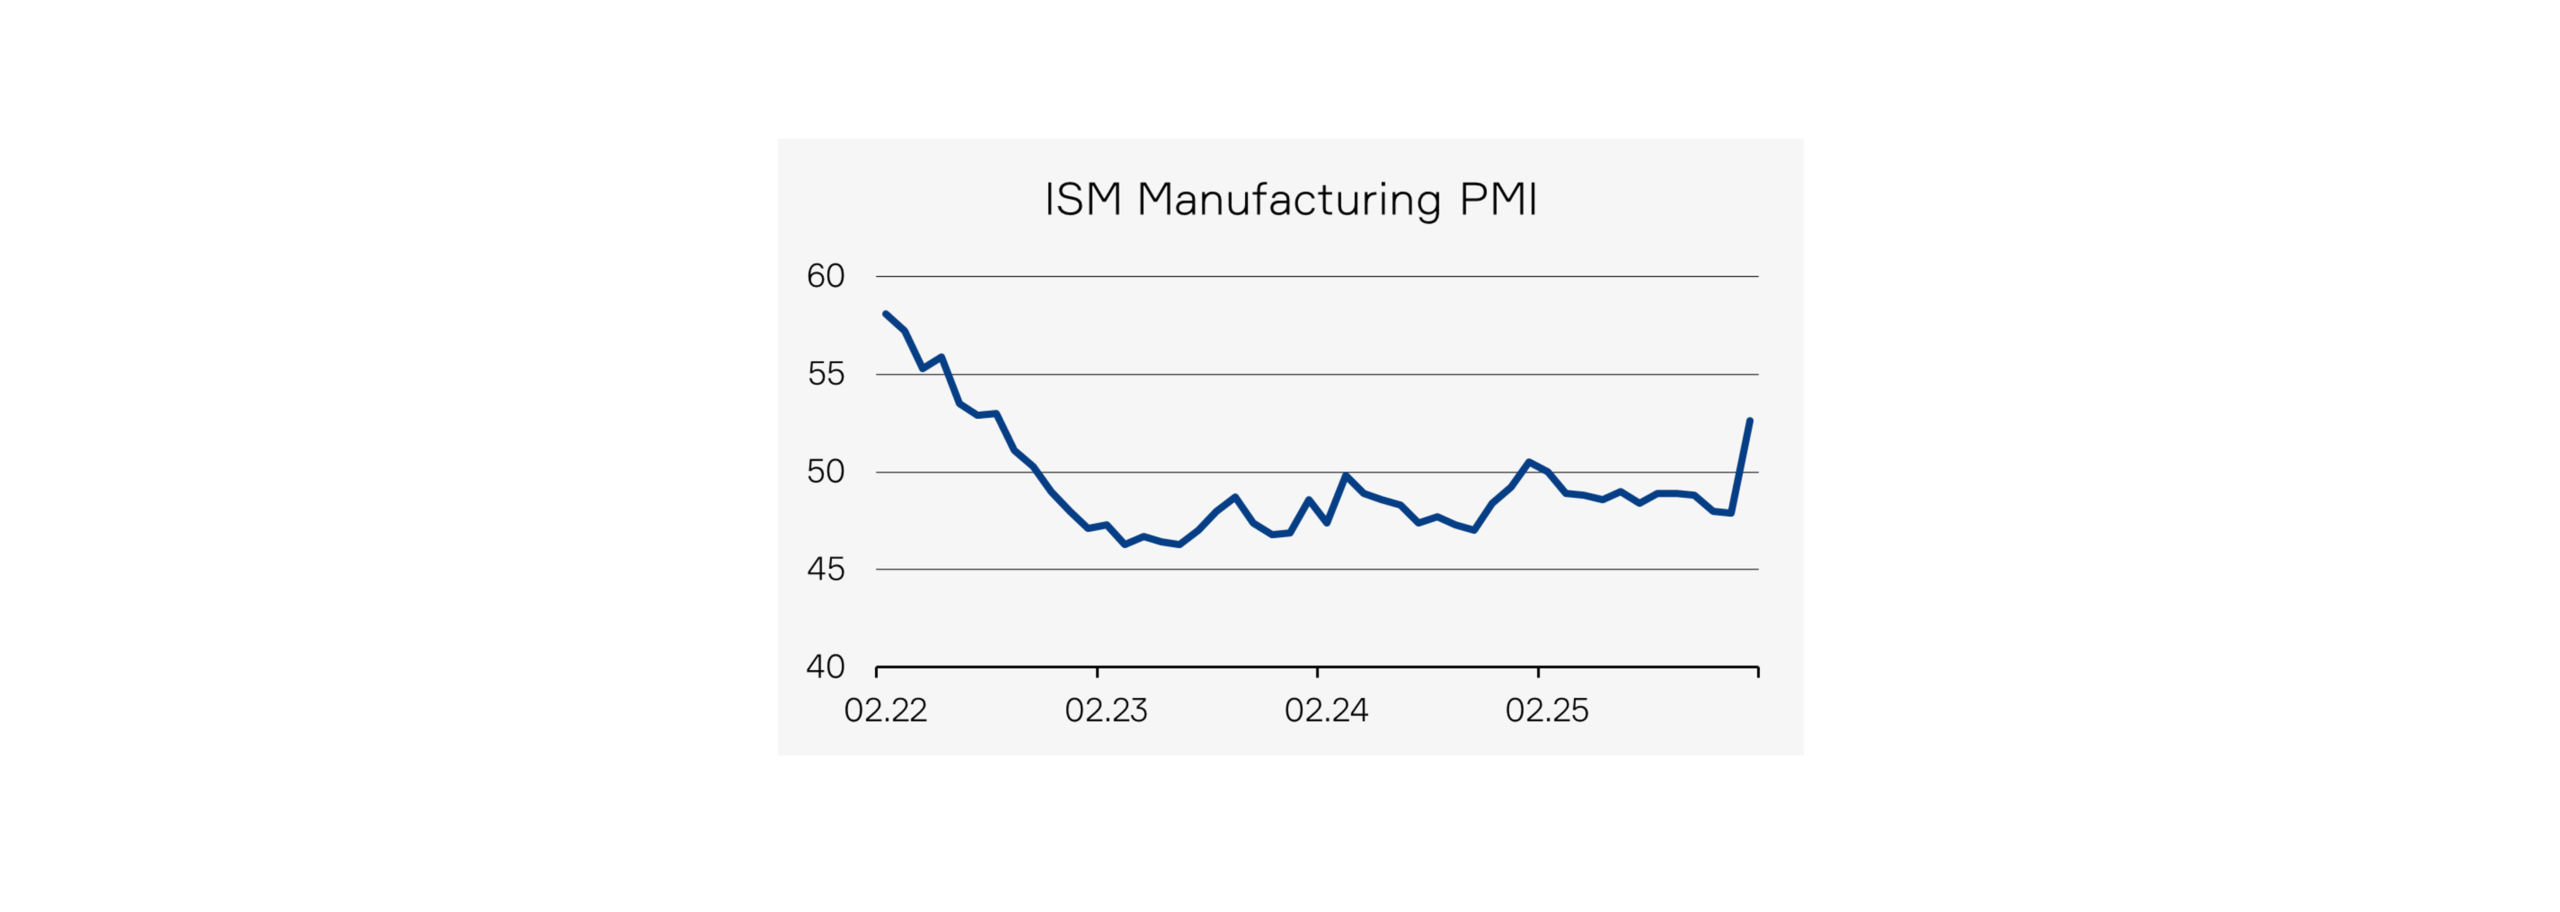
For companies, this means increasingly broad-based earnings growth, which provides a solid foundation for rising stock markets over the remainder of the year.
Stock rotation in full swing
This change in growth momentum is not without consequences on the markets. We have been observing a pronounced rotation in equities for several months now. Small & mid caps, emerging markets and the cyclical sectors of industry, energy and basic materials are showing clear relative strength and have clearly outperformed the global equity index.
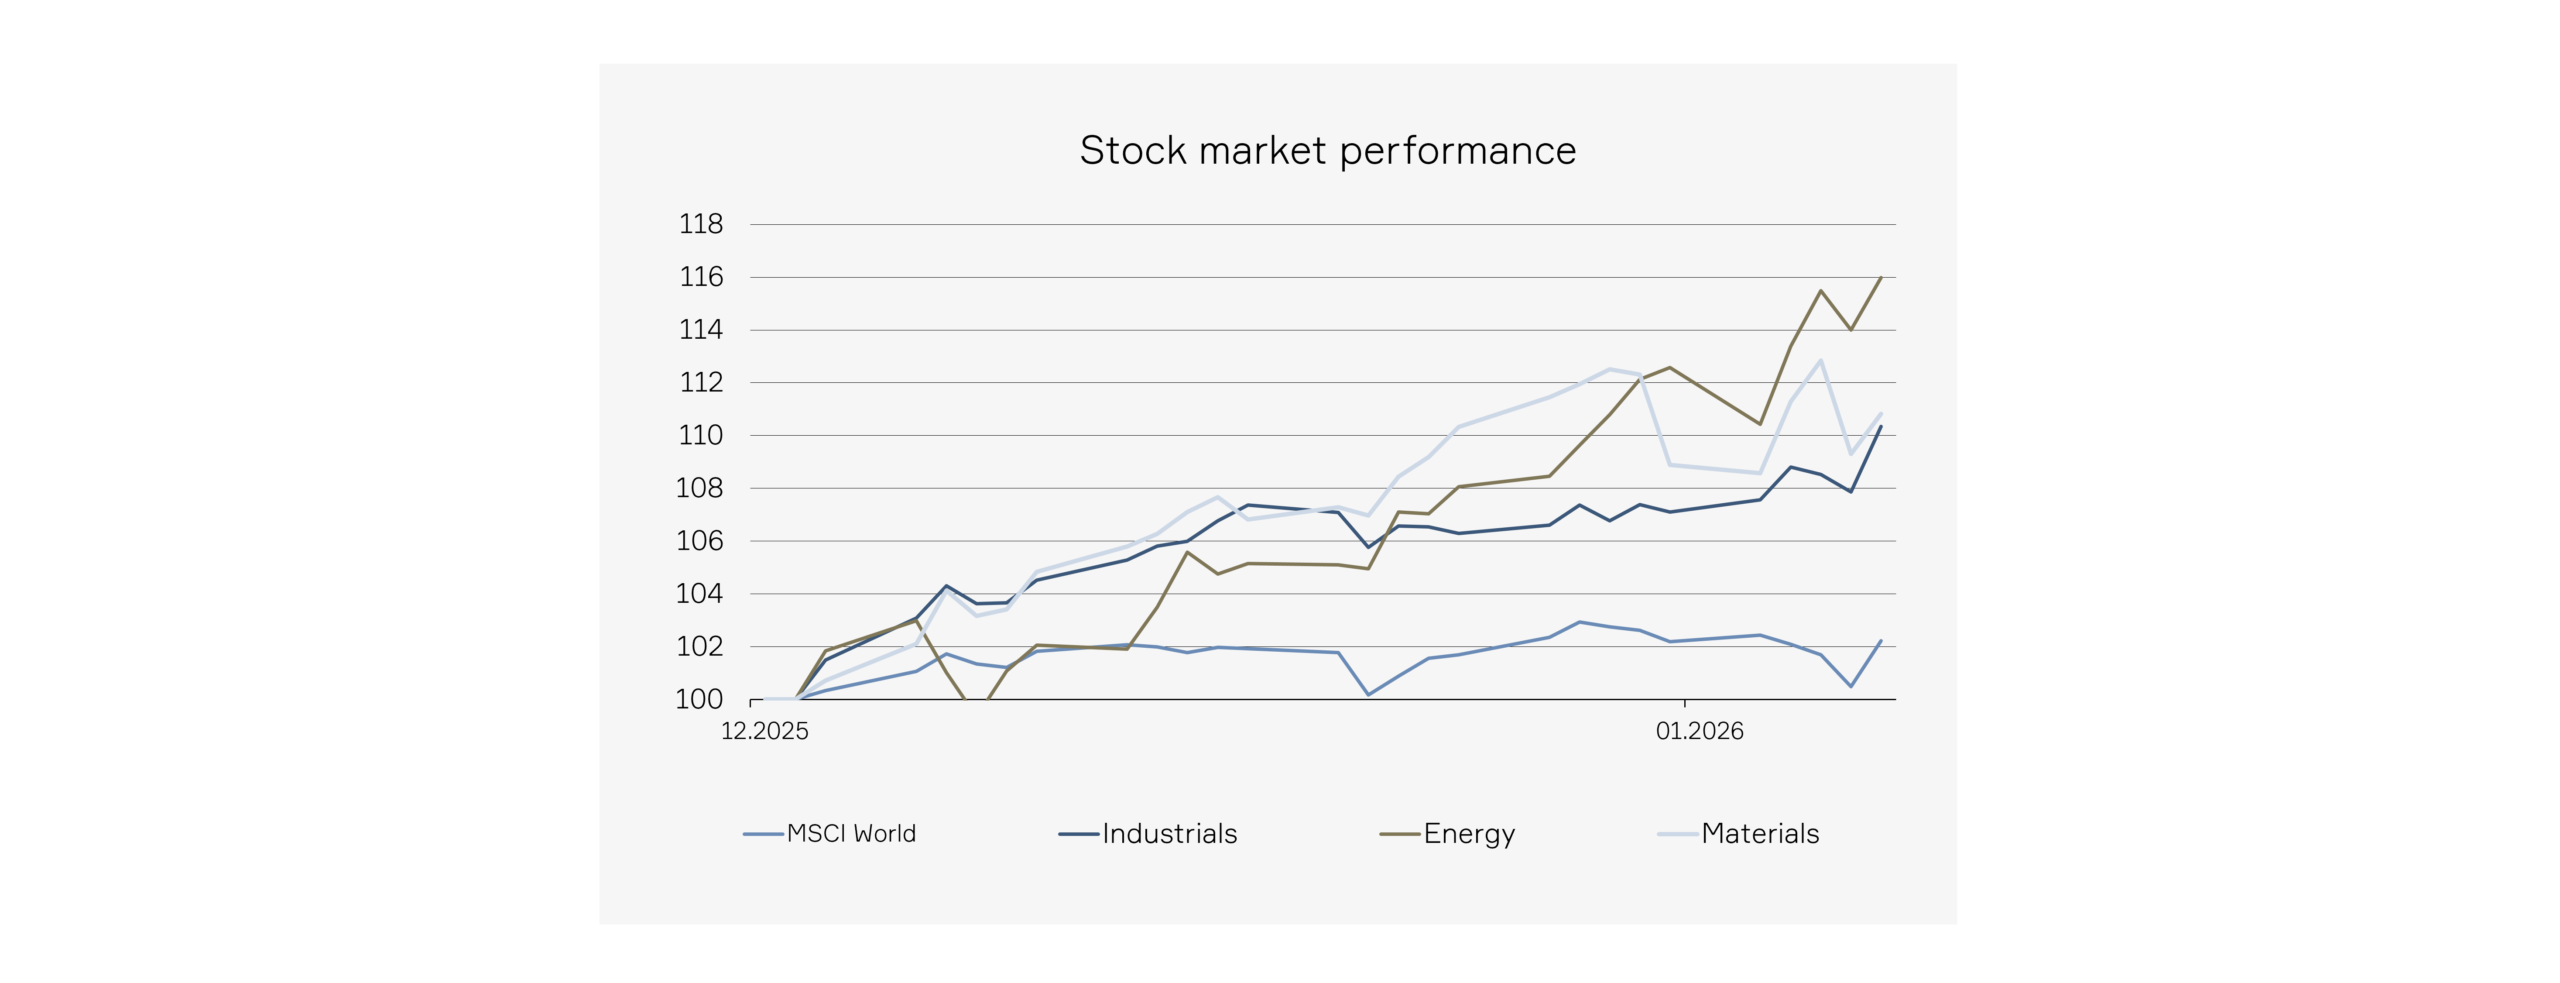
Despite this development, valuation discounts remain considerable. At the same time, these market segments remain underrepresented in many global portfolios. Both of these factors point to further catch-up potential, particularly in an environment in which growth is more broadly based again.
Opportunities are also opening up in the technology sector. The recent sell-off in software stocks allows investors who are underinvested in this sector to selectively build up positions. Global market leaders such as Microsoft and SAP as well as the strategically important cybersecurity sector appear attractive.
Targeted portfolio adjustments
A changing world requires not only active stock selection, but also a rethink of asset allocation. For decades, the classic portfolio of equities and bonds worked reliably: Bonds cushioned recessions, equities ensured real asset growth. However, the framework conditions have shifted. A protectionist trade policy, the commodity-intensive restructuring of infrastructure and escalating government debt worldwide are fundamentally changing the risk landscape. The dominant portfolio risk today is no longer deflationary shocks, but recurring bouts of inflation and a creeping devaluation of money.
The protective function of bonds is diminishing in this context, especially when you consider the modest yield levels. The search for alternatives is challenging, but not hopeless. We are focusing on gold, selected cryptocurrencies, private infrastructure investments and commodity-related equities. This positioning is flanked by a high proportion of Swiss francs and targeted partial hedging of the US dollar risk.
In the face of global upheaval, we see adaptability and foresight as crucial ingredients in ensuring the resilience of our portfolios and continuing our impressive track record.
Publisher: Tareno AG, Gartenstrasse 56, 4052 Basel, Tel. +41 61 282 28 00, info@tareno.ch, www.tareno.ch. We welcome feedback on our publication. This content is for information purposes only. The publication contains neither legal nor investment advice or investment recommendations and does not constitute an offer or solicitation to make an investment.
Images / graphics: The graphics were produced by Tareno AG from public market data.
Do you have any questions on this topic?
Our portfolio management team will be happy to provide you with explanations and clarifications.
Find out more about us
Asset management
Publications