Sector rotation as an opportunity
May 13, 2026
Extraordinary rally
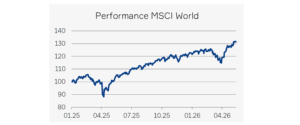
An agreement between the USA and Iran has yet to be reached, meaning that the transportation of oil and gas through the Strait of Hormuz has been largely blocked for over ten weeks. As a result, energy prices remain at a high level, inflationary pressure is rising globally and interest rate expectations are being adjusted upwards. Despite these headwinds, the global equity markets have already more than compensated for the decline in March.
Fundamentally supported
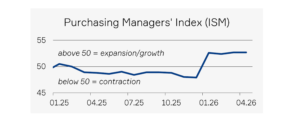
The optimism on the stock markets is well-founded, as the global economy is coping with the energy crisis better than expected. Companies and consumers are responding by increasing efficiency, making strategic adjustments and utilizing reserves along the entire value chain. At the same time, there are strong tailwinds from generous fiscal policy and an investment boom, particularly in the expansion of data centers and AI infrastructure. As a result, leading indicators are still clearly in growth territory and confirm the economy’s resilience.
Impressive profit growth
This resilience is not only reflected in the economic data, but also in the corporate results. According to the results of the current reporting season so far, global earnings growth of 21% is emerging.
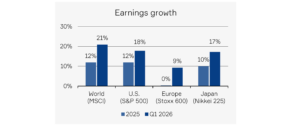
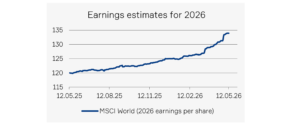
In addition, the estimates for 2026 as a whole have been continuously revised upwards in recent months.
Unlike in previous years, however, growth is no longer solely attributable to large technology companies. Other sectors as well as small and medium-sized companies are also recording higher growth than in previous years.
Utilizing sector shifts
However, the market does not adequately reflect this breadth: currently, companies that benefit from the AI boom are strongly favored.
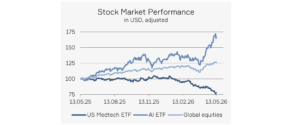
Against the backdrop of increasing sector differences, we consider targeted reallocations to be sensible:
- Reduction of individual, rapidly growing positions in the AI area
- Expansion of exposure in the healthcare sector, particularly in the medical technology segment, which is attractive in the long term and currently offers a very good risk/reward profile
However, our recommendation for asset allocation remains unchanged: remain fully invested as part of the strategic equity allocation.
This content is for information purposes only. The publication contains neither legal nor investment advice or investment recommendations and does not constitute an offer or solicitation to make an investment. joPictures / Graphics: The graphics were produced by Tareno AG from public market data.
Do you have any questions on this topic?
Our portfolio management team will be happy to provide you with explanations and clarifications.
Find out more about us
Asset management
Publications